Murabaha is one of the most widely used contracts in Islamic banking. It allows a customer to acquire an asset, such as equipment, goods or a vehicle, and pay for it over time, without an interest-bearing loan.
What Murabaha means
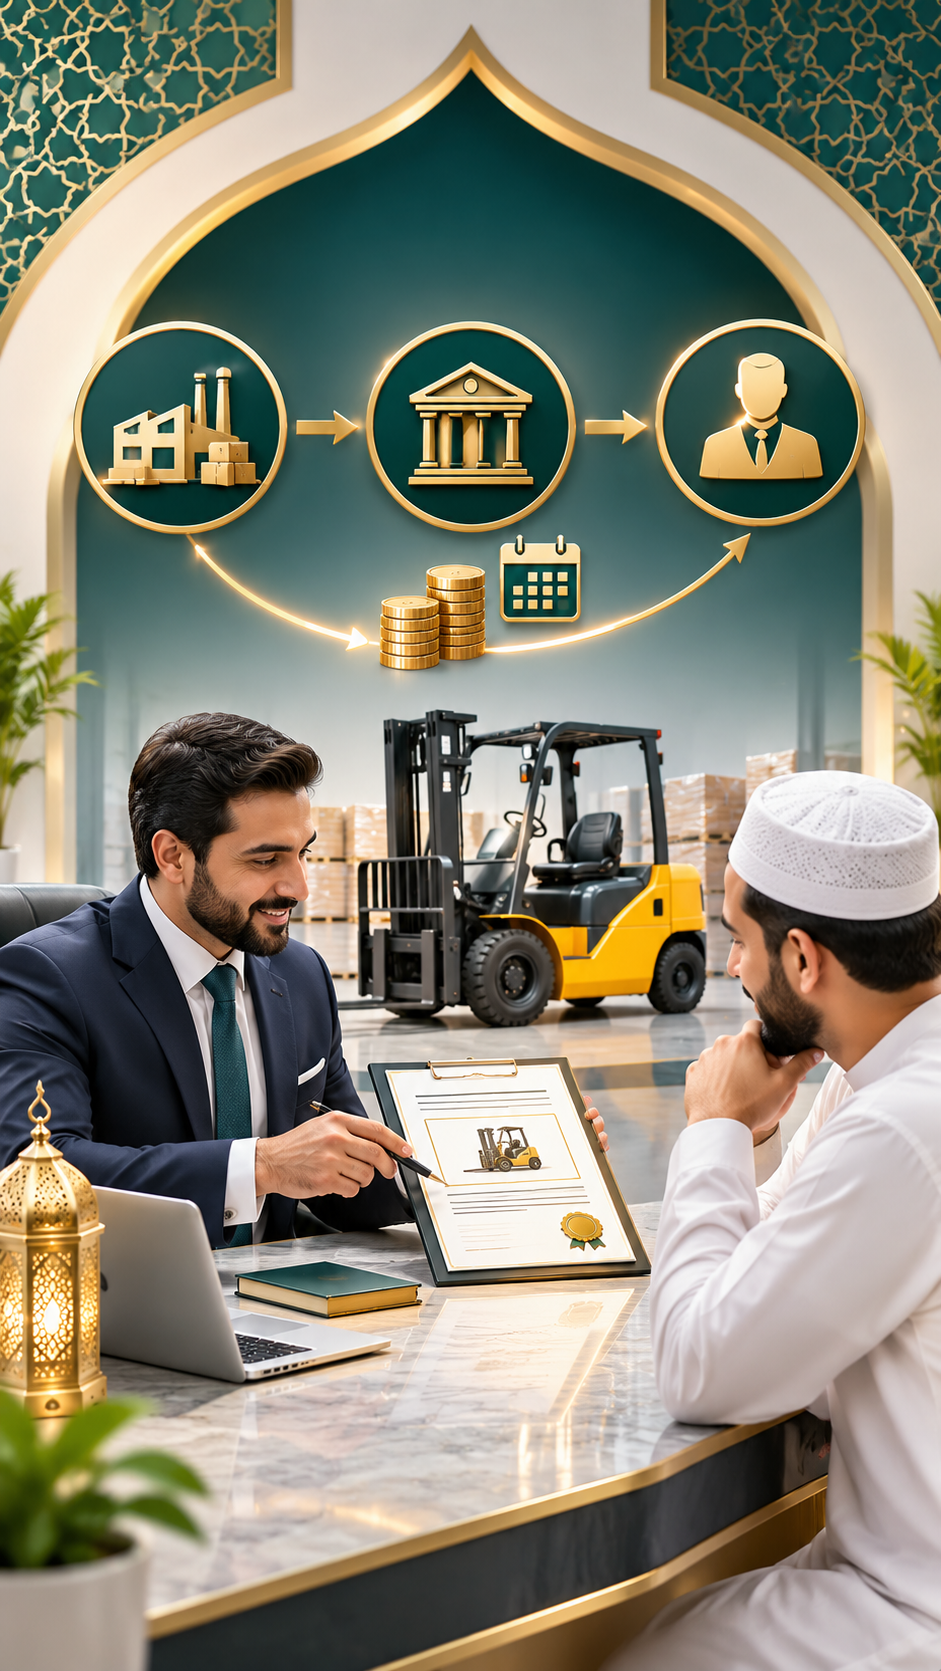
Murabaha is a sale in which the seller tells the buyer the cost of the goods and the profit added to it. In Islamic banking, the bank buys the asset the customer needs and then sells it to the customer at cost plus an agreed profit, usually on deferred payment.
How it works, step by step

Why it is different from a loan
The bank earns its profit from selling an asset it actually owned, not from lending money. Once the sale is agreed, the price is fixed. It cannot be increased if the customer pays late. Where late payment charges are agreed to discourage delay, they are commonly given to charity rather than kept by the bank as income.
Where it often goes wrong
Problems usually arise when the steps are followed on paper but not in reality. Common issues include the bank selling the asset before it owns it, documents signed in the wrong order, or the customer acting as the bank's agent without proper records. This is why a Shariah review of the process, and not only the contract, matters.
Our training Shariah Compliance in Practice walks through a real Murabaha review step by step.